Does homeowners insurance cover fire damage cleanup in West Palm Beach?
Most West Palm Beach homeowners policies cover fire damage cleanup, smoke removal, and rebuild - but the details decide your payout. Here's how claims actually work.
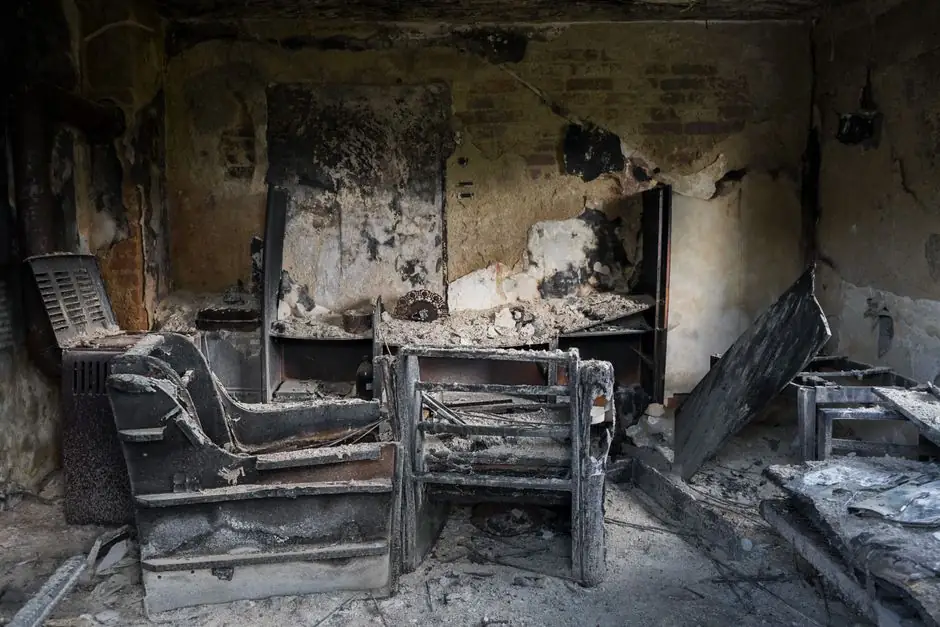
Yes - a standard Florida HO-3 homeowners policy covers fire damage cleanup in West Palm Beach, including smoke removal, soot cleaning, water damage from firefighting, and the rebuild itself. Fire is the one peril every HO-3 policy is required to cover, and Florida insurers cannot exclude it the way they exclude flood or hurricane wind. What actually decides your payout is not whether fire is covered - it is how the claim is documented, what your dwelling limit is set to, and whether you use a restoration company that knows how to write a scope an adjuster will approve.
We have walked hundreds of West Palm Beach homeowners through this exact process, from kitchen fires in El Cid bungalows to sprinkler discharges in downtown high-rises. Below is what is covered, what is not, what cleanup costs in 2026, and the mistakes that quietly cost people thousands.
The short answer: yes, with conditions
Fire damage restoration is the process of stabilizing a fire-damaged home, removing smoke and soot residue, drying water left by firefighting, and rebuilding the structure to pre-loss condition. Your insurance covers that work - but only the parts tied to a covered peril, and only up to the limits you chose when you bought the policy.
Three numbers on your declarations page control almost everything:
- Dwelling coverage (Coverage A) - the structure itself. In West Palm Beach, most single-family homes carry $350,000 to $700,000 in Coverage A, which tracks rebuild cost, not market value.
- Personal property (Coverage C) - furniture, clothing, electronics. Commonly 50-70% of Coverage A.
- Loss of use (Coverage D) - hotel and meals while your home is uninhabitable. Typically 20% of Coverage A, and it usually caps out around 12 months.
If your Coverage A is $400,000, you are looking at roughly $200,000-$280,000 for contents and $80,000 for temporary housing. Those are the real ceilings on your claim, no matter what the damage totals.
What a standard West Palm Beach policy actually pays for
A West Palm Beach fire claim is not one line item - it is a stack of them, and each one has its own documentation standard. Here is what we routinely see approved.
Emergency services and board-up
The moment the fire department leaves, your home is open to rain and theft. Board-up and roof tarping is covered as an emergency measure, usually under a separate $3,000-$10,000 sublimit. We handle this the same night so the claim does not grow while everyone waits for paperwork.
Water damage from firefighting
A single 1¾-inch fire hose moves 100-250 gallons per minute. Ten minutes of suppression can put 2,000 gallons into your floors, ceilings, and wall cavities. That water is covered because it came from a covered peril - the fire. Drying and dehumidification typically run $2,500-$8,000 for an average West Palm Beach home and are almost always approved when documented with moisture readings.
Smoke, soot, and odor
Smoke travels through HVAC returns and pressurizes rooms the fire never touched. Soot is acidic and etches brass, chrome, and appliance finishes within 72 hours. Odor removal - thermal fogging, hydroxyl generators, ozone - is covered, but insurers want to see air quality readings before and after. We take those readings on day one.
Contents, electronics, and documents
Pack-out, off-site cleaning, and storage of salvageable contents are covered. So is document and electronics restoration for items like laptops, tax records, and family photos. Replacement cost coverage pays to replace rather than depreciate - worth checking on your policy, because it changes a $4,000 payout into a $12,000 one.
Rebuild and code upgrades
Reconstruction is the biggest line item. Florida's building code requires upgrades when you rebuild - impact glass, updated electrical, current wind mitigation. Most policies include 10-25% additional coverage for ordinance and law upgrades, but only if you ask for it.
What fire damage cleanup usually is NOT covered
The exclusions matter as much as the coverage. These are the ones that surprise West Palm Beach homeowners most often.
- Vacant homes. If the house sat empty more than 30 consecutive days, most policies void fire coverage entirely. This catches snowbirds who leave for the summer.
- Intentional acts. Arson by an insured party is excluded. So is damage from a fire you set while committing a crime.
- Poor maintenance. A fire caused by a dryer vent packed with three years of lint may be denied as neglect. Insurers do inspect.
- Mold after the fire. Mold that existed before the fire is excluded. Mold that grew because the claim sat for three weeks is a fight - and one we usually win when drying started on day one.
- Landscaping and fencing. Usually capped at $500-$1,000 total.
- Cash, jewelry, and collectibles. Capped at $1,500-$2,500 unless you scheduled them separately.
One more: if your home is in a flood zone and the fire was followed by storm water intrusion, that water is a flood claim, not a fire claim. Two policies, two adjusters, two deductibles.
How the claim process works after a West Palm Beach house fire
The claim clock starts the moment the fire is out, not the moment you feel ready to deal with it. Here is the sequence that keeps a claim clean.
- Call your insurer within 24 hours. Report the loss and get a claim number. Florida law gives you a right to prompt acknowledgment, and delays invite scrutiny.
- Do not throw anything away. Charred debris is evidence. We photograph and inventory everything before it leaves the property.
- Get a professional scope, not a contractor's estimate. An adjuster approves line items - square footage of drywall, cubic feet of contents, gallons of water extracted. A one-page estimate gets a one-page settlement.
- Meet the adjuster on site. We walk the property with your adjuster, point out hidden damage, and document what they miss. This single step is where most claims gain or lose 20-40%.
- Track your additional living expenses. Keep every hotel and restaurant receipt. Coverage D does not pay what you cannot prove.
Most West Palm Beach fire claims settle in 30-90 days for the structure and longer for contents. If your adjuster is slow, Florida's Department of Financial Services takes complaints and that usually moves things.
How much fire damage cleanup costs in West Palm Beach in 2026
Typical 2026 pricing in this area runs like this, and these are the numbers your adjuster will compare your estimate against.
- Board-up and roof tarp: $800-$3,500
- Water extraction and structural drying: $2,500-$8,000
- Smoke and soot cleaning, 1,500-2,500 sq ft home: $4,000-$12,000
- Odor removal with air quality testing: $1,200-$4,500
- Contents pack-out, cleaning, and storage: $2,000-$9,000
- Full reconstruction after a kitchen fire: $35,000-$120,000
- Full rebuild after a total loss: $180-$320 per square foot
A contained kitchen fire in a 1,800-square-foot West Palm Beach home usually lands between $18,000 and $45,000 all-in. A total loss on the same house runs $325,000 to $575,000. Your deductible - commonly $2,500 to $5,000 for fire on Florida policies - comes off the top.
Common mistakes that shrink a fire damage claim
We see the same five errors over and over, and each one costs real money.
Waiting to call. Soot etches within 72 hours. Mold starts at 48. Every day of delay converts a cleaning job into a replacement job, and insurers push back on damage they consider preventable.
Cleaning it yourself. Household cleaners smear soot into porous surfaces and can strip finishes. We have re-cleaned kitchens where a homeowner's efforts added $3,000 to the bill - and the insurer refused that portion.
Accepting the first offer. The first settlement is an opening number. Missing line items - HVAC duct cleaning, attic insulation, subfloor replacement - are the norm, not the exception.
Not documenting before cleanup. Photos of the damage as it was found are the backbone of the claim. Once debris is in a dumpster, that evidence is gone.
Letting a general contractor handle the insurance scope. Restoration is its own trade with its own pricing standards. A GC who mostly builds new homes will underwrite the drying and deodorization phases, and you will pay the difference.
When to call a professional
Call us the same day if any of these are true: the fire department used water inside the house, smoke reached rooms the fire did not, you can smell smoke from the front door, or your HVAC was running during the fire. Those four conditions mean the damage is already wider than it looks.
Our team handles Emergency Fire Damage Restoration in west palm beach around the clock, and we document the loss the way adjusters want it documented - moisture readings, air quality samples, photo inventories, and a line-item scope that matches industry pricing software. We also handle Insurance claim assistance for fire damage in west palm beach, which means we sit in the room with your adjuster so nothing gets missed.
If you are in an older neighborhood, this matters more. The 1920s bungalows around WPB Fire Damage Restoration in El Cid have original knob-and-tube wiring in some attics and plaster walls that hold smoke odor far longer than modern drywall. Downtown high-rises bring the opposite problem - sprinkler discharges that soak multiple units and trigger three separate claims. We work both, and we know which one your adjuster will question.
Frequently Asked Questions
Does homeowners insurance cover smoke damage if there was no fire?
Yes, if the smoke came from a covered peril - a kitchen flare-up, a neighbor's fire, or a furnace puffback. Most West Palm Beach policies treat smoke as part of the fire peril, so cleanup, odor removal, and contents cleaning are covered up to your limits. Damage from a wildfire is also covered under standard HO-3 policies.
How long do I have to file a fire damage claim in Florida?
Florida law requires you to report a claim promptly, and most policies set a one-year deadline for filing suit and a two-year deadline for supplemental claims. In practice, report within 24 hours. Waiting weeks gives your insurer grounds to question whether the damage happened as described.
Will my premium go up if I file a fire claim?
Usually yes, by 10-25% at renewal, and a second fire claim within five years can lead to non-renewal. That said, a $40,000 fire loss is not something to absorb out of pocket to protect a premium. File the claim, then shop your policy at renewal.
Does insurance pay for a hotel while my house is being repaired?
Yes, through Coverage D, typically up to 20% of your dwelling limit and often capped at 12 months. A $400,000 Coverage A gives you roughly $80,000 for temporary housing and meals. Keep every receipt - reimbursement is based on what you can document.
Can I choose my own restoration company?
Yes. Florida law prohibits insurers from requiring you to use a specific contractor. Your insurer can question the price, but not the choice. We work directly with every major carrier and bill them directly so you are not fronting the full cost.
Get help with WPB Fire Damage Restoration in west palm beach
If your home has fire, smoke, or water damage, the first 48 hours decide how much of your claim gets approved. We board up, dry out, clean, and rebuild - and we handle the paperwork with your adjuster so you are not translating between a contractor and an insurance company alone.
Call WPB Fire Damage Restoration at +1 (561) 562-7610 for a same-day assessment anywhere in west palm beach.